Online Casino Payment Methods for Australians
 Available in AU
Deposits, withdrawals, fees and verification can follow different rules, while a payment option does not establish that the underlying gambling service is lawful.
Table of Contents
- Payment Routes and the Difference Between Deposits and Cashouts
- Deposits and Withdrawals Follow Different Timetables
- Australian Bank Transfers: PayID, BPAY and Local Constraints
- Payment Gateways: Availability Is Not the Same as a Cashout Route
- Payment Systems and the Verification Step
- Payment Portals: Check the Conditions Before Funding
- Provider Fees Can Change the Amount Received
- Instant Payments: Fast Deposits Do Not Settle Every Question
- Payment Apps and Wallet-Based Deposits
- Mobile Payments: Set the Spend Limit Before the Transaction
Payment Routes and the Difference Between Deposits and Cashouts
Payment discussions often group bank transfers, e-wallets, prepaid cards and cryptocurrency under the broad heading of casino payment options. Those categories describe ways money can move between accounts; they do not establish that a real-money casino service is lawful or available to people in Australia. The distinction matters because the Interactive Gambling Act 2001 prohibits operators from providing online casino-style games, including pokies, poker and table games, to customers physically located in Australia.
A specialist review identifies bank transfers, e-wallets, prepaid cards and cryptocurrencies as categories relevant to Australian payment comparisons. That is a description of a review’s coverage, not an endorsement or evidence that any route can lawfully be used for online casino gambling in Australia. The same caution applies to phrases such as “online casino payment solutions”: a payment channel may exist as a financial product without making the underlying gambling service permitted.
The categories work differently at a basic level. A bank transfer moves funds between bank accounts. An e-wallet holds or routes funds through a separate payment account. A prepaid card limits the amount available to the value loaded onto it. Cryptocurrency transfers use digital assets rather than a conventional bank balance. These descriptions are not interchangeable, and none settles the legal status of the service receiving a payment.
Choosing a casino payment method means checking the details that matter to you, such as the available deposit options and their terms. This list provides a starting point for reviewing operators, with only the supplied licensing and deposit information noted.
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.) SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
License: Curacao – Antillephone N.V. (Versus Odds B.V.) · Min. deposit: EUR 20 Thor Casino is licensed in Curacao through Antillephone N.V. (Versus Odds B.V.). Its stated minimum deposit is EUR 20.
License: Curacao Gaming Control Board (TechSolutions Group N.V.) Bizzo Casino is listed with a Curacao Gaming Control Board licence held by TechSolutions Group N.V.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) GoldenCrown is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Min. deposit: A$15 LevelUp Casino is listed with a Curacao eGaming licence, OGL/2023/174/0082, held by Dama N.V. Its stated minimum deposit is A$15.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Rollero Casino is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
License: Curacao eGaming OGL/2024/923/0383 (Antillephone N.V.) · Min. deposit: A$30 WinSpirit Casino is listed with a Curacao eGaming licence, OGL/2024/923/0383, held by Antillephone N.V. Its stated minimum deposit is A$30.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd.
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board licence.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is described as a Curacao operator that has been operating since 2017. Its stated minimum deposit is A$20.
Bitcoin is one cryptocurrency that appears in payment discussions, but its presence in a list of payment methods does not make a casino Bitcoin payment lawful in Australia. Nor does a payment route’s technical availability show that an operator may provide real-money casino games to Australians. A familiar brand, an Australian-dollar display, or an accessible payment screen would not alter the prohibition on operators.
One useful distinction within payment comparisons is between money going into an account and money coming back out. A specialist review notes that casino payment methods can differ between deposits and withdrawals. In practical terms, a method shown for funding an account cannot be assumed to be available for a payout. The route may be limited to one direction, or the operator’s listed options may differ between the two transaction stages. The deposit menu alone therefore cannot establish the cashout route.
That distinction is separate from processing speed, provider charges or identity checks. Those details affect the mechanics and final amount of a transaction; they do not determine whether an Australian-facing casino service is lawful. Treating the payment menu as a complete account of the arrangement would confuse a technical option with permission to provide the gambling service.
Searches for a phone payment casino or for newer payment names such as Revolut and Volt raise the same basic issue. A name in a payment discussion is not proof of a supported transaction route, and support for a transaction would not make prohibited online casino services compliant with Australian law. Payment brands and operator menus can change; the legal restriction on providing real-money online casino games to people in Australia remains the governing context.
For any comparison of payment routes, the direction of funds is a separate field from the method name: deposit, withdrawal, or both. That distinction is useful for understanding how payment arrangements are described, but it should not be mistaken for a recommendation to fund an offshore casino account. No payment category—bank transfer, e-wallet, prepaid card or cryptocurrency—changes the legal position.
Deposits and Withdrawals Follow Different Timetables
A payment route’s value is measured differently when money is leaving an account. The relevant figures are the time until funds arrive and the amount remaining after charges. A quick account credit says nothing about either. For an Australian audience, there is also a prior legal constraint: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The payment details below describe reported cashout mechanics, not an endorsement of using such a service.
Bank transfers can involve an operator-side queue before the bank processes anything. A specialist review describes casino withdrawals as being handled manually once or twice a week, with a Friday request potentially arriving by Wednesday. That is a reported example, not a timetable that applies across operators. The delay may sit in the operator’s processing schedule rather than in the transfer itself, so a stated bank-processing time does not necessarily represent the full wait.
A reported example of bank transfer processing shows that a request made on Friday may not arrive until the following Wednesday due to operator-side queues
The same specialist review characterises bank transfer as slow but potentially suitable for withdrawals above $10,000. That makes the route more relevant to a large balance than to a need for prompt access, but the amount alone does not establish when funds will arrive. Timing depends on the stated processing arrangement, while the final amount depends on charges and any currency conversion. Those details belong in the cashout terms, not in a deposit-speed comparison.
Fees change the net result. A specialist review reports flat bank-transfer charges of $5–$15 at casinos it assessed, while describing crypto withdrawals as generally free of casino fees. Neither statement establishes a universal tariff. A fee-free withdrawal can still incur a network cost, and a nominally simple transfer can lose value through a separate charge. The useful comparison is therefore the amount expected to reach the destination, not merely the fee label shown beside a method.
Cryptocurrency settlement has its own timing variables. One specialist review puts Litecoin withdrawals at about 10 minutes and says Bitcoin can take up to an hour when its network is congested. Those are reported estimates, not guaranteed arrival times. Network conditions matter, and the time displayed for a transaction does not necessarily cover any operator review before it is sent. A faster blockchain estimate should not be treated as a promise of faster overall cashout.
The risk profile also differs from that of a bank transfer. Blockchain transactions are irreversible and do not offer a chargeback option. An incorrect address or an unsuitable network can therefore create a loss that cannot be reversed through a card dispute. The apparent absence of a casino withdrawal fee does not remove that exposure; it only addresses one possible deduction.
A practical comparison can be kept to three figures: the operator’s processing window, the expected settlement time after release, and the amount received after charges. For bank transfers, the manual queue and flat fee may be the larger variables. For cryptocurrency, network congestion and irreversibility carry more weight. Neither route can be assessed from its advertised speed alone, and no cashout estimate establishes that a real-money casino service is lawful to provide in Australia.
Australian Bank Transfers: PayID, BPAY and Local Constraints
PayID and BPAY are Australian bank-payment services, but their presence in a payment menu says nothing about whether the underlying gambling service is lawful. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people in Australia. That includes pokies, poker and table games. A payment route that appears to accept Australian dollars does not change that legal position or amount to evidence of Australian regulatory approval.
PayID connects a mobile number, email address or Australian Business Number to a bank account through the New Payments Platform. It is supported by every major Australian bank, giving it broad reach across domestic banking. That reach describes the banking infrastructure, not universal acceptance by gambling operators. Whether a particular service displays PayID depends on the operator and its payment arrangements.
Legal Prohibition
Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino-style games, including pokies, poker and table games, to customers physically located in Australia.
A specialist review describes PayID as the primary Australian-dollar deposit option at most offshore operators. That is a time-sensitive account of those operators’ payment menus, not a fixed feature of the Australian market. Menus can change, and a method listed for adding funds does not establish that it is available for taking funds out. More importantly, accepting a local transfer does not make an offshore casino compliant with Australian law.
BPAY has a different practical profile. A specialist review gives its payment timing as one to two business days, making it slower than a route designed for immediate account-to-account processing. The same type of review characterises BPAY as rarely used for real-time play and as a possible fallback when PayID is unavailable. Those descriptions concern reported use and timing; they should not be read as a guarantee that a particular service accepts BPAY or credits a payment on a particular schedule.
The distinction matters when comparing Australian casino payment methods. PayID’s bank coverage may make it recognisable, while BPAY’s processing window can make it less suited to situations where funds are expected to appear promptly. Neither feature establishes the status of a service offering real-money casino games to Australians. Local payment access and legal permission are separate questions.
Payment labels also need to be read narrowly. “PayID accepted” identifies a route for a transaction only if the operator’s terms specify what that route can do. It does not, by itself, tell whether the service supports the method in both directions, how it handles a transaction, or whether the operator is authorised to provide the gambling product in Australia. BPAY’s presence has the same limitation. A familiar domestic payment name is not a substitute for examining the service behind it.
There is no contradiction between PayID’s broad banking support and the possibility that it will not appear in a given payment menu. The bank network can support a method while an individual merchant or platform does not offer it. BPAY can likewise be available through banks yet absent from a particular service’s options. The relevant distinction is between what Australian banks support and what an offshore operator chooses to display.
For Australian readers, the central point is therefore not which bank transfer looks faster. PayID and BPAY are established parts of the local payment landscape, but their technical availability cannot legitimise a prohibited online casino service. A domestic transfer channel remains a payment channel; it does not confer Australian approval on the recipient.
Payment Gateways: Availability Is Not the Same as a Cashout Route
A payment gateway is the checkout layer that connects a payment choice to a transaction. Its logo or name on a cashier page shows, at most, that the option is displayed there. It does not establish that the same route can return funds, that the operator will accept a particular transaction, or that the service is lawful in Australia.
That distinction matters when an option appears to support deposits but offers no corresponding way to receive a balance. A specialist review reports that PayID availability for deposits varies by operator and that withdrawal support must be checked separately. The practical test is therefore two-sided: confirm the route for money entering an account and independently confirm the route for money leaving it. A gateway name alone does not answer both questions.
Do
- Confirm the route for money entering an account
- Independently confirm the route for money leaving it
- Check the method’s stated purpose and currency
Don’t
- Assume a gateway logo confirms a cashout route
- Treat a deposit-only option as a full payment plan
- Rely on a cashier page as a general endorsement
The cashier should be read as a transaction map, not as a general endorsement. Check the method’s stated purpose, the currency shown, and whether the available options change between deposit and withdrawal screens. If a payment method is listed only at checkout, its presence is not evidence that it can process cashouts. Where terms are unclear, the route remains unconfirmed; treating an assumption as a payment plan is poor accounting.
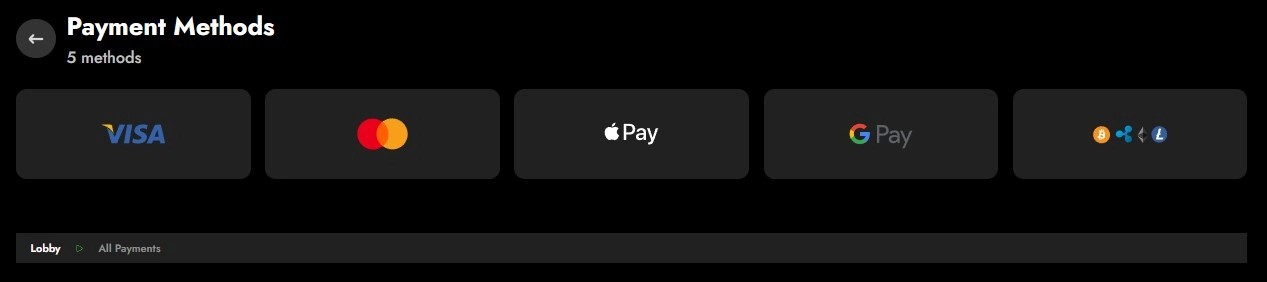
The same standard applies to digital-wallet labels. Apple Pay or Google Pay appearing as a deposit option does not make either a withdrawal route. Klarna appearing in a payment context would not, by itself, establish that a casino transaction is supported or that funds can be returned through it. The gateway and the underlying payment service are separate parts of the chain, and a name at one point in that chain proves little about the rest.
Payment technology also cannot resolve the legal question. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino services—including pokies, poker and table games—to people located in Australia. A functioning payment gateway does not change that rule, and a cashier page is not evidence of Australian authorisation.
For a clear record, each method needs its own entry: deposit availability, withdrawal availability, and any conditions attached to each direction. If one side is absent or ambiguous, the method is not a complete payment route. That is a material limitation, not a minor interface detail. A deposit option can move money in; only a separately supported cashout route can move it back.
Payment Systems and the Verification Step
A casino payment system can involve more than the transfer itself. Account checks may determine whether a transaction can be processed, and the evidence requested can relate both to identity and to the payment method. A specialist review reports that an operator may ask for official identification, a document confirming an address dated within the previous three months, and evidence showing ownership or use of the payment method.
Those are separate checks, not interchangeable documents. Identification relates to the account holder; address evidence relates to where that person is recorded as living; payment evidence connects the account to the funding method. If a request covers all three, providing only one category does not answer the others. The practical point is that a payment system’s screen may show a transaction step, while the operator may still need account evidence before it can proceed.
The exact document request can depend on the operator. A general description of casino payment systems therefore cannot establish what a particular service will accept. The account terms and any direct request from the operator are the relevant references for the documents required. A file should correspond to the requested category rather than merely contain personal information.
Account Verification
Provide a valid government-issued ID to verify the account holder’s identity.
Submit a document confirming the residential address dated within the previous three months.
Provide evidence showing ownership or use of the specific payment method being employed.
This distinction matters where payment software presents a smooth sequence of buttons and confirmation messages. A completed instruction on screen is not, by itself, evidence that the account check has been completed. The process has two parts: the payment instruction and the operator’s assessment of the account and payment evidence. Treating the first as proof of the second is a bookkeeping error.
The same principle applies across different payment labels. Searches for an online casino payment system may bring up references to CashtoCode, eCheck or SMS payments, but a method name says nothing about the identity evidence an operator may request. Nor does it establish that the method is available, lawful, or suitable for a person in Australia. Real-money online casino services are prohibited for operators under the Interactive Gambling Act 2001 when offered to people physically located in Australia. Payment terminology does not alter that position.
For any payment service, “safe” cannot be concluded from the use of a branded interface alone. The relevant questions are narrower: what information is requested, which account or payment it relates to, and whether the transaction is being offered within the law. An operator’s request for official identification, address evidence, or proof of payment method should be read as a condition attached to its process, not as a guarantee that the service is compliant or that funds are protected.
A careful record of the requested documents and the account details they relate to can make discrepancies easier to identify. Names or payment references that do not align may prompt clarification, but the specific outcome depends on the operator’s process. No payment interface can substitute for checking the legal status of the service itself.
Payment Portals: Check the Conditions Before Funding
A payment portal is the point where an account’s transaction terms meet the payment choice. Its display of a method does not establish that the activity is lawful in Australia, nor does it make the account’s other conditions irrelevant. Under the Interactive Gambling Act 2001, operators may not provide real-money online casino games to people physically located in Australia. A payment screen cannot change that position.
For any account terms being assessed, the key distinction is between the payment transaction and the offer attached to the account. A deposit can be recorded as complete while a separate promotional condition remains outstanding. The displayed balance alone may therefore not represent an amount that can be withdrawn without further requirements.
No-deposit promotions are a clear example. “No deposit” describes the absence of an initial payment; it does not, by itself, settle what must happen before winnings can be withdrawn. Such promotions may carry wagering requirements, identity or account verification, and withdrawal conditions. Each condition affects a different part of the calculation: wagering terms govern what must be done with the balance, verification concerns the account evidence required, and withdrawal terms determine whether funds can be paid out.
Those conditions should be read together rather than as isolated labels. A promotion may look cost-free at entry while still imposing obligations that affect access to any resulting balance. If the wording separates eligibility, wagering, verification and withdrawal rules across different pages, the practical terms are the combined set. A headline offer is not a substitute for that set.
Attention A “no deposit” promotion does not guarantee immediate withdrawal; it may be subject to wagering requirements, identity verification, and specific withdrawal conditions.
The same discipline applies to a casino payment platform or portal before any transaction is considered. The amount entered, the account balance shown, and the conditions governing a promotion are not interchangeable figures. A portal may present the first two prominently while placing restrictions elsewhere. The relevant question is not simply whether a payment button appears, but what conditions attach to the account and whether the transaction is lawful in the first place.
Searches for a particular online casino payment method, including POLi, Boku, Neosurf or PayPal, do not answer those account-level questions. PayPal has expressly prohibited gambling transactions in Australia since 2021. A name or logo on a screen is not evidence that a service is authorised for a particular purpose, and it does not establish that a promotion can be converted into a withdrawable amount.
A useful review therefore separates three matters: the legality of the service, the terms attached to the account, and the payment transaction itself. Promotional wording should be checked for wagering, verification and withdrawal conditions before it is treated as a statement of value. Where those conditions are unclear, the amount available for withdrawal cannot be calculated from the headline offer alone.
Provider Fees Can Change the Amount Received
A payment provider’s charge can reduce a withdrawal after the casino has approved it. The amount credited to a bank account therefore depends not only on the requested cashout, but also on the route’s stated transaction fee. Skrill is one example: a specialist review reports that transfers from Skrill to a bank take one to two days, while some casinos apply a transaction fee of one to three per cent. The fee is not presented as a universal Skrill charge; it is a condition attached to some casino transactions and needs to be checked in the applicable terms.
That percentage changes the net amount received. If a fee is deducted from the transfer, the bank credit is lower than the amount sent. If it is charged separately, the effect is instead an additional cost. The terms should make clear which calculation applies, and whether the fee belongs to the casino or the provider. A quoted withdrawal time also describes settlement, not the size of the final credit.
MuchBetter is described in a specialist review as faster for withdrawals than a traditional bank transfer, for which the review gives a possible wait of up to five days. That comparison concerns timing, not a guaranteed cashout window for every account. It also does not establish that the faster route has no fee. Speed and cost are separate entries in the calculation; treating one as a substitute for the other obscures the amount ultimately received.
Neteller presents a different cost point. A specialist review reports a 1.45% charge when funding the wallet by credit card. That is a wallet-funding fee, not a withdrawal fee, so it should not be added to a casino cashout calculation as though it were deducted from winnings. Credit cards are not an appropriate deposit route for online gambling in Australia, and this fee is relevant only as a description of the provider’s stated funding cost—not as a recommendation to use that route.
Transfers to a bank take one to two days, with some casinos applying a 1–3% transaction fee.
Reported as faster for withdrawals than traditional bank transfers, which can take up to five days.
Features a 1.45% charge specifically for funding the wallet via credit card.
For any payment provider, the useful comparison is the net settlement: the requested amount, any casino deduction, any provider fee, and the time taken for the transfer to reach the bank. A headline such as “fast withdrawals” leaves the fee question unanswered; a low fee says nothing about settlement speed. The terms should identify the charge and the point at which it is applied.
These figures describe claims made in specialist reviews, not fixed market-wide conditions. Fees and processing times can vary with the provider, casino terms, account status and transaction route. In Australia, this comparison does not make real-money online casino services lawful: the Interactive Gambling Act 2001 prohibits operators from providing those services to people physically located in the country.
Instant Payments: Fast Deposits Do Not Settle Every Question
A card payment can clear quickly without being a usable route for an Australian customer. A specialist review describes Visa and Mastercard deposits at offshore casino sites as instant, but that timing refers to the payment step, not whether the transaction will be accepted by an Australian bank. Those are separate checks, and speed does not resolve either the legal status of the service or the bank’s decision.
A separate specialist review reports that Australian financial institutions now block many standard Visa and Mastercard payments directed to offshore casinos. The qualification matters: “many” does not mean every card transaction, while a payment page displaying a card logo does not confirm that a particular transaction will go through. A declined payment is not made more viable by being described as instant.
The Australian legal position is also distinct from processing time. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including pokies, poker and table games, to people located in Australia. A payment method’s presence in an offshore site’s cashier does not change that restriction or establish that the service is permitted in Australia.
The useful comparison is therefore not simply between instant casino payment methods and slower ones. It is between a stated processing speed and a transaction’s actual availability in the Australian context. Card deposit speed answers only the first question. It does not establish that an Australian financial institution will process the payment, and it does not demonstrate that the underlying casino service can lawfully be offered to people in Australia.
Terms such as online casino payment Interac, Neteller or MiFinity may appear in payment discussions, but they do not alter the same distinction: a named method or a casino payment integration is not evidence of legal permission or successful processing. For Australian residents, claims about instant funding cannot be treated as a recommendation to use an offshore casino. A displayed option is a technical detail, not a permission slip.
Payment Apps and Wallet-Based Deposits
A phone-based payment flow can make funding an account feel like a single tap, but the app does not determine whether the underlying service is lawful or whether money can be returned through the same route. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people located in the country. A payment option appearing on a site does not change that position.
PayID utilizes the New Payments Platform to link Australian bank accounts with identifiers like mobile numbers, email addresses, or ABNs.
PayID uses the New Payments Platform to connect an Australian bank account with an identifier such as a mobile number, email address or ABN. That link is between the identifier and the account; it is not, by itself, evidence that a casino transaction is available. A specialist review describes PayID availability as dependent on the operator and says withdrawal support needs separate confirmation. Those are two distinct checks: an option displayed for adding funds does not establish that it can be used to receive a payout.
Apple Pay works through a phone’s digital wallet, with biometric authentication used to approve a deposit, according to a specialist review. That describes the payment step, not the status of the service receiving the money. Nor does it establish an Apple Pay cashout route. Apple Pay should not be treated as a withdrawal method.
The useful comparison is therefore about transaction direction, not convenience. For PayID, confirm whether the specific account supports the intended transaction before any funds are moved; deposit availability and withdrawal eligibility are separate. For Apple Pay, the cited detail concerns deposits only. Neither an app icon nor a successful authorisation provides evidence of Australian regulatory approval.
This distinction also matters when a payment page displays multiple wallet names. A label alone does not establish that a wallet can be used on a phone, that it is supported for both directions, or that a casino service may lawfully be offered in Australia. Terms such as EcoPayz, Paysafecard, UPI and ACH may appear in searches or payment menus, but their presence there does not establish an Australian app flow or cashout option.
The transaction should be assessed on what the service actually permits and what the law allows, rather than on how quickly a phone confirms a payment. A completed payment is not a compliance check.
Mobile Payments: Set the Spend Limit Before the Transaction
A prepaid voucher sets a clear ceiling on the amount available for a transaction: spending cannot exceed the value loaded onto it. That makes the cost visible before funds are used, rather than leaving the payment tied to a bank balance. The control is limited, however. It caps the voucher-funded amount; it does not make an online gambling service lawful or establish that money can later be returned through the same route.
The cashout limitation matters more than the payment label. Voucher-funded deposits generally cannot be sent back to the voucher, so a separate withdrawal route is needed if a balance is to be paid out. A mobile casino payment made with a voucher is therefore one-way in practical terms: the voucher can provide funds, but it should not be treated as a cashout destination. Any assessment of the transaction has to account for both sides before money is committed.
This distinction also applies when a payment page presents a voucher as a simple mobile option. A fixed loaded value offers spending control, but it does not resolve how a withdrawal would work. If no separate cashout route is available, the voucher’s spending limit does not solve the resulting access problem. The relevant calculation is the amount placed at risk and the route, if any, for returning funds—not the ease of completing the initial payment.
In Australia, real-money online casino games provided to people physically in the country are prohibited under the Interactive Gambling Act 2001. Payment mechanics do not alter that legal position. A prepaid voucher’s cap is a transaction limit, not evidence that an online casino service is authorised or that any balance is protected under Australian consumer law.
For mobile payment decisions, the practical distinction is therefore between controlling the amount spent and having a workable way to receive money back. A voucher can do the first within its loaded value; it should not be assumed to do the second.
Written by the editors at Oscarspin Casino.